15
Notifications 15
(NISM)

The National Institute of Securities Markets (NISM) is a public trust established in 2006 by the Securities and Exchange Board of India (SEBI), the regulator of the securities markets in India. The institute carries out a wide range of capacity building activities at various levels aimed at enhancing the quality standards in securities markets.

How Capital Gains Tax Works in India: A 2026-27 Investor’s Guide

If you’re confused about capital gains tax on your investments in listed shares, mutual funds, and ETFs, you’re in the right place. The rules have evolved significantly, especially with the Income-tax Act, 2025, now governing the Tax Year 2026-27. Let me take you through with a few examples so you know exactly what you owe.

The two sides of capital gains: short-term vs. long-term

The first thing you need to understand is that your tax rate depends entirely on how long you held the investment. The tax authorities reward patience.

1. What counts as short-term?

For listed equity shares and equity-oriented mutual funds, if you sell within 12 months or less, your profit is classified as a Short-Term Capital Gain (STCG). Under the current framework, this is taxed at a flat 20%.

Let me put this in perspective: If you bought shares for ₹1,00,000 and sold them 10 months later for ₹1,20,000, your STCG is ₹20,000. You’ll owe ₹4,000 in tax on that gain.

2. What counts as long-term?

If you hold those same equity investments for more than 12 months, your gains become Long-Term Capital Gains (LTCG). The rate here is 12.5% on gains exceeding ₹1.25 lakh in a financial year.

The ₹1.25 lakh annual exemption

The annual exemption of ₹1.25 lakh means you can make that much profit every single year completely tax-free. It resets every financial year. Let’s see this with an example.

Assuming you sold listed shares in January 2027 (Tax Year 2026-27) and made a total LTCG of ₹3,07,000.

Here’s how your tax is calculated:

  • Total LTCG: ₹3,07,000

  • Less: Annual exemption: ₹1,25,000

  • Taxable LTCG: ₹1,82,000

  • Tax @ 12.5%: ₹22,750

  • Health & Education Cess @ 4%: ₹910

  • Total tax payable: ₹23,660

Notice your effective tax rate is only about 7.7%, not 12.5%. The exemption reduces what you actually pay. So, you may consider selling enough long-term holdings each year to realize up to ₹1.25 lakh in gains. You pay zero tax, and when you buy them back, your new cost basis is higher, reducing future taxable gains. This is known as “tax harvesting.”

Not all mutual fund gains are taxed at the same rate

The tax treatment of mutual funds depends on what the fund actually holds. We can think of them as three distinct buckets.

1. Bucket 1 – Equity funds (≥65% equity)

These funds invest at least 65% in domestic equity shares. They enjoy the same favorable treatment as listed shares i.e. 20% STCG for holdings up to 12 months, and 12.5% LTCG for holdings beyond 12 months, with the ₹1.25 lakh exemption applying.

2. Bucket 2 – Hybrid funds (>35% to <65% equity)

These funds don’t qualify as equity. If you hold them for 24 months or less, gains are taxed at your slab rate. For holdings beyond 24 months, LTCG is taxed at 12.5%, but the ₹1.25 lakh exemption does not apply.

3. Bucket 3 – Debt funds (Specified Mutual Funds)

From FY 2025-26, any mutual fund investing more than 65% in debt and money-market instruments is classified as a “Specified Mutual Fund” under Section 76 of the Income-tax Act, 2025. Gains from these funds are treated as short-term capital gains, irrespective of how long you hold them. They are taxed at your applicable slab rate, even if you held them for a decade.

For tax treatment of ETFs check the underlying asset

The tax treatment of ETFs depends entirely on the scheme classification and the underlying assets.

ETF Type ≤12 Months >12 Months
Equity ETF 20% 12.5% (Above ₹1.25L)
Gold ETF Slab rate 12.5%
Silver ETF Slab rate 12.5%
Debt ETF Slab rate Slab rate

Let me show how much tax you have to pay if you invest in Gold ETFs with an example.

Suppose you invested ₹2,00,000 in a Gold ETF in June 2026 and sold it in August 2027 for ₹2,50,000, after holding for 14 months. Sale value: ₹2,50,000. Gain: ₹50,000.

Here is how your tax is calculated:

Holding period: 14 months → LTCG

LTCG rate for Gold ETF: 12.5%

Gain: ₹50,000

Tax: 12.5% of ₹50,000 = ₹6,250

Health & Education Cess @ 4%: ₹250

Total tax payable: ₹6,500

Now, what if you had sold after just 10 months? Your gain would be a Short-Term Capital Gain, taxed at your income tax slab rate. If you fall in the 30% bracket, your tax would be ₹15,600 including cess, which is more than double the long-term tax amount. The lesson we can take from here is that Gold ETFs reward patience.

Also, notice that the ₹1.25 lakh annual exemption does not apply to gold ETFs. It is applicable to Equity ETF investments of more than 12 months.

Set-off and carry-forward in case of capital loss

Any loss on investment is bad news. But what many investors do not realise is that it can become a powerful tax-saving tool. The Income Tax Act allows you to set off capital losses against capital gains in the same year. Your Short-Term Capital Loss (STCL) can offset both STCG and LTCG. However, your Long-Term Capital Loss (LTCL) can offset only LTCG.

And if you can’t use the entire loss in one year, you can carry it forward for up to 8 years, provided you file your income tax return by the prescribed due date.

Let me show you how this works with an example.

Suppose you trade in stocks and mutual funds. In the financial year 2026-27, you have a mixed bag of results:

Your Gains:

  • Short-Term Capital Gain (STCG) from selling shares held for 8 months: ₹3,00,000

  • Long-Term Capital Gain (LTCG) from equity mutual funds held for 3 years: ₹2,00,000

Your Losses:

  • Short-Term Capital Loss (STCL) from selling a stock: ₹1,50,000

  • Long-Term Capital Loss (LTCL) from selling a property: ₹80,000

Here is how your tax is calculated:

Short-Term Capital Gain: ₹3,00,000

Set-off Short-Term Capital Loss: ₹1,50,000

Taxable STCG: ₹1,50,000

Tax payable (equity): 20% of ₹1,50,000 = ₹30,000


Long-Term Capital Gain: ₹2,00,000

Set-off Long-Term Capital Loss: ₹80,000

Annual exemption: ₹1,25,000

Taxable LTCG: ₹2,00,000 – ₹80,000 – ₹1,25,000 = ₹0

Tax payable: ₹0


Tax payable (STCG+LTCG): ₹30,000

Health & Education Cess @ 4%: ₹1200

Total tax payable: ₹31,200


What if you have more losses than gains and can’t fully set-off your losses in the current year? You can carry forward your losses to next year. So, keep track of your unadjusted losses year by year, don’t let them lapse.

Knowledge is your best strategy

Learning about taxes that affects your investment, shouldn’t be an afterthought. It helps you make better informed decisions.

If you want to go deeper, I recommend NISM’s Skill Development Module (SDM) on Taxation in the Securities Market. It covers everything from capital gains and STT to derivatives and buybacks, all in about 2 hours of focused, expert-led content. For a modest fee of ₹500, you get a structured, comprehensive understanding of how taxation impacts your securities market decisions.

Remember, tax laws evolve. So, when in doubt, speak with a qualified tax advisor about your specific situation.

Author: Sandeep K Biswal, DGM
Trusting AI with Your Money is Subject to Market Risks

Trusting AI with your money is subject to market risks

If you have asked ChatGPT, Gemini or Claude any money question this year, be it tax on your mutual fund redemption, or whether to prepay your home loan, or how NPS withdrawal works, you are not alone. Millions of people turn to AI chatbots for financial guidance before they turn to human intelligence, simply because it is free, instant, and does not require an appointment. The trouble is, as suggested by a new study, the answer you got back may have been wrong, and worst of all, you would have had no way of knowing. After all, there is no free lunch!

Saturn, a UK fintech firm that builds tools for financial advisers, commissioned a study in July 2026. They asked an experienced paraplanner to test 18 of the most widely used AI models against 121 real-world money questions. Each question was asked five times per model, since AI answers can vary from one attempt to the next, producing over 10,000 responses in total. Every answer was measured against a strict standard: it had to contain every figure, deadline, rule and warning that a qualified adviser would consider essential.

The results were shocking to say the least. The overall accuracy rate across all 17 current models was 43 per cent. That means if you asked an AI chatbot a financial question, the answer was either wrong or incomplete more often than it was right. On harder, multi-step questions the failure rate rose to 88 per cent. Even on simple questions, the kind a first-time investor might ask about what a term means or how a product works, accuracy was only 54 per cent.

Further, the free chatbot advice (which most investors fall for) was accurate only 37 per cent of the time against roughly 51 per cent for paid ones (43 percent average). If AI is meant to widen access to financial guidance, it is currently doing that unevenly.

What kind of mistakes are made by these AI models ? Not vague or philosophical ones. The study’s examples shows that the errors AI models make are the ones most investors will reply on to make a financial decision. One such question posed to a free model was which debts should a person pay-off first? The model answered to prioritise the ones with the highest interest rate, without mentioning that unpaid rent or a missed council tax bill. The missed rent or tax bill carries a far more serious risk in the UK than a high-interest credit card. Translate that to an Indian household juggling a personal loan, a credit card bill and rent, and the same blind spot could apply.

The AI models also invent rules that do not exist also called as hallucination. For instance, the bot told a student exploring studying at UK that her loan repayment would simply stop once she leaves UK permanently. Likewise, an advice on pensions would have exposed the investor to an unauthorised-payment tax charge of up to £17,500 (roughly ₹22-23 lakh at current exchange rates).

AI can inform investment decisions, but cyber risks demand awareness. Strengthen your understanding of cyber security and resilience with NISM-IFSCA-02A: Certification Course on Cyber Security and Cyber Resilience in the GIFT IFSC (Basic).

Build Cyber Resilience. Get Certified.

 
The detail that should worry the investors most is that the wrong answers sounded exactly like the right ones. The study found that models rarely flagged uncertainty, and gave no signal that a question might be beyond what they could reliably answer. A confident, fluent, well-structured wrong answer is far more dangerous than an uncertain one, because you have no clue to go check it elsewhere.

There is no equivalent Indian study yet, so we do not know our exact numbers, and this remains a UK-specific finding rather than direct evidence about Indian outcomes. But there is little reason to assume Indian financial questions are easier for these models to get right. The queries on capital gains tax, indexation changes, NPS and EPF choices, prepayment of home loans and mutual fund taxation in India is as layered as in the UK. Further India-specific rules are likely to make up a far smaller share of any AI model’s training data than UK or US rules do, and that could easily raise the error rate here. It is worth noting here that SEBI’s investor survey found that 62 per cent of investors say they are influenced by finfluencers, many of whom offer no accountability or verified track record. That is precisely the vulnerability a general-purpose AI chatbot can deepen further, quietly, and without ever being called a finfluencer at all.

So, what should you do differently? Treat an AI chatbot’s financial answer the way you would treat a stranger’s confident opinion at a dinner party –worth paying attention to, not worth acting on unchecked. Use it to understand a concept or draft the questions you should ask a professional, not to make the final call on anything involving tax, debt prioritisation, or retirement withdrawals. If a chatbot gives you a specific number, a threshold, a deadline, or a tax figure, verify it against a primary source, the income tax department’s site, your fund’s own factsheet, or an actual adviser, before you rely on it. And be most cautious exactly where the study found AI to be weakest: complex, multi-part questions with real money and real deadlines attached, not general  queries. The responsibility sits with you as the investor to treat AI-generated financial advice as a first draft, not a final answer, especially where taxes, debts, and retirement money are on the line.

Author: Rachana Baid, Dean – Academics (NISM)

Note:

The article is originally published in Mint: https://www.livemint.com/money/personal-finance/ai-chatbots-financial-advice-accuracy-risks/amp-11791784853049.html

Passive Investment Funds: Why Retail Investors Choose Them

Why are retail investors voting with their wallets for passive products?

The Assets under Management (AuM) of passive equity funds, as of 31st March, 2025, was about 27% of the overall equity fund AuM of Rs.40 lakh crores. The AuM of passive equity funds have grown at a CAGR of 47% in the last 5 years, significantly outstripping the growth in AuM of actively managed equity funds. In this period the number of passive folios grew at 68% as compared to a meager 21% growth in active folios.

And therein lies a fascinating paradox – this explosive growth in AuM and folios of passive equity funds has happened even though many active equity funds have delivered better returns, with lower volatility, in comparison to their passive counterparts.

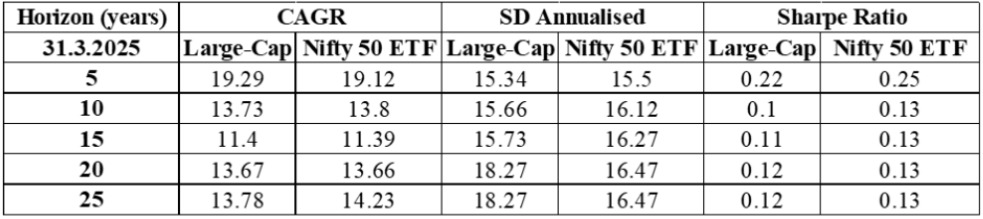
An analysis of fund returns over a 25 year period indicate that, over many time periods, large cap equity funds have outperformed the NIFTY 50 ETFs. Their volatility adjusted returns – measured by risk indicators like the Sharpe Ratio – match those of the NIFTY 50 ETFs.

Managers of active funds have the ability to avoid index laggards, allocate tactically to outperforming sector and exercise judgement during periods of market stress. In theory, therefore, given their track record and the promise to deliver alpha, should not investors prefer active funds? Yet the fund flows tell a different story.

There are several structural and behavioral factors that explain why retail investor tilt towards ETFs and Index Funds. Firstly, retail investors find it difficult to identify which active fund manager will deliver alpha in the future. While some active large cap funds have outperformed their benchmark over the last 25 years, the consistency of such outperformance is not uniform and they have had periods of underperformance. Passive funds, in contrast, almost guarantee market matching returns without the uncertainty. In times of market volatility, retail investors become wary of “manager risk” – the risk that a chosen fund manager may underperform. Passive investing eliminates this layer of decision making.

Secondly, ETFs and Index Funds have some structural advantages. As ETFs trade like stocks, they offer inter-day liquidity. They offer complete transparency of holdings, as they mirror the underlying index, thus easing portfolio construction for asset allocators. Younger investors are less emotionally attached to the idea of star fund managers and more focused on efficient exposure to asset classes. For investment advisors, recommending ETFs or Index Funds, simplifies client communication and portfolio monitoring.

Thirdly, passive funds have a clear cost advantage. Expense ratios of ETFs and Index Funds are significantly lower than those of actively managed funds. Even if active fund managers outperform their passive counterparts by 200 basis points, their higher fees can erode their net advantage. Over long periods, compounding of this fee difference can tilt the scales in favor of passive funds. For instance, as can be seen the table above, actively managed large cap funds have, on average for a 25-year period, delivered a CAGR of 13.78% compared to the CAGR of 14.23% delivered by the NIFTY 50 ETFs. This would mean that Rs.10,000 invested in a NIFTY 50 ETF in the year 2000 would now be worth Rs.2.78 lakhs whereas Rs.10,000 invested in a large cap fund would be worth only Rs.2.52 lakhs.

For a new generation of investors, who prefer predictability, simplicity, transparency and lower costs, investing in passive funds aligns with their financial philosophy.

Understand Passive Investing Better.

 
Author: Shri Sashi Krishnan, Director – NISM

What stops retail investors from moving from fixed deposits to a corporate bond?

The Indian corporate bond market has grown from ₹17.5 lakh crore at the end of FY15 to over ₹60 lakh crore today. The minimum face value of a bond has come down to ₹10, 000. Online bond platforms are now regulated. However, retail investors hold just ₹1.2 lakh crore of corporate bonds compared to ₹152 lakh crore of fixed deposits. Has the time come for retail investors to reassess their debt asset allocation?

While deciding on asset allocation, investors look at three things – potential returns, risks associated with the investment and liquidity of the asset class. Doubtless, corporate bonds tend to deliver better returns than fixed deposits. ₹1,00,000 invested in a three-year fixed deposit, which yields 6.75% today, will grow to ₹1,22,239. The same money invested in a AAA corporate bond at today’s yield of 7.60% will grow to ₹1,24,566, ₹2,327 more over three years. An investment in a BBB bond at today’s yield of 13% will grow to ₹1,44,290, which is ₹22,647 more than what a fixed deposit gives. Even the safest bonds give better returns than deposits. Returns from lower-rated bonds, as expected, are substantially ahead of fixed deposit returns.

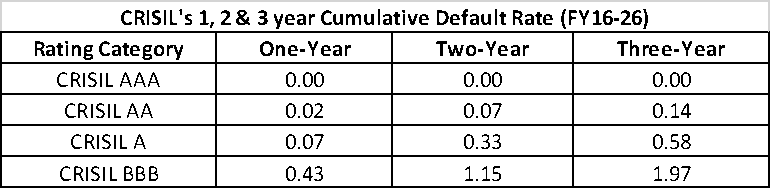
The extra return that bonds deliver comes with extra risk. How then should investors evaluate this extra risk? While bonds do carry the risk of non-payment of principal and interest, it should not be the reason to stay away from investing in them. The CRISIL Default and Rating Transitions Study 2026 suggests that the probability that an entity rated AAA will default within 3 years is 0%. The probability that an entity rated BBB will default within 3 years is just 1.97%. Over a shorter 1-year horizon, the probability that the BBB-rated bond will default is much lower at 0.43%.

Another possibility is a bond getting downgraded. Any downgrade impacts the market price of bonds. This matters only if the investor needs to sell the bond before maturity. If an investor intends to hold the bond to maturity, she need not be too concerned, as the issuer keeps paying interest and she will get the principal on maturity. CRISIL data indicates that the probability of a AAA bond being downgraded to a rating below AAA is very low. The probability of a BBB bond being downgraded to a lower rating is also less than 5%.

Liquidity is another issue retail investors are worried about. A deposit has no market price, and it can be broken on any working day, though early withdrawal does carry the risk of a reduced interest rate. Liquidity for corporate bonds, on the other hand, varies widely. Highly rated bonds are liquid, but for lower-rated bonds, liquidity is often a problem. This has been partially addressed by the 29 online bond platforms that now operate in the market. These platforms have made buying a bond as easy as opening a deposit, though selling a bond can still pose a problem as markets are thin. As more retail investors start participating in the bond market through these platforms, the secondary market should deepen.

What a fixed deposit offers retail investors is not a superior rate of return but the certainty of exit. Money that may be needed at short notice will, obviously, find its way into deposits. However, investment-grade bonds held to maturity are now an alternative for retail investors, especially for their long-term financial goals. Better returns, not too high risks, and improving liquidity make this an attractive asset to own.

Strengthen Your Wealth Management Expertise

Deepen your understanding of financial planning, asset allocation, investment products, risk management and portfolio management with the NISM & CRISIL Certified Wealth Manager programme.

 
Author: Shri Sashi krishnan, Director – NISM

The minds inside a derivatives account

The minds inside a derivatives account

SEBI’s Department of Economic and Policy Analysis has published a series of studies on individual traders in the equity derivatives segment since January 2023, the latest pair in August 2026. It is unusual for a regulator anywhere to publish this candidly on the losses of the investors it supervises. The August 2026 study of trading behaviour is the most valuable of the lot, because it does not stop at how much individuals lost and starts asking how they traded. In other words, it is less a statistics report than a behavioural report. Almost every headline number lines up with a bias that behavioural finance has documented for decades. The data does not merely tell us that individuals lose money in derivatives. It tells us how they talk themselves into it.

Overconfidence, and the illusion that experience teaches.

Time in the market does not help, at least not here. Among traders with one consecutive year of participation, 91 per cent made losses. The share rises with every additional year, reaching 96.5 per cent at four years. Among traders active through all five years from FY22 to FY26, only 0.5 per cent were profitable in every year. This learning curve slopes the wrong way, because what survives repetition is not skill but conviction. Traders do not learn that they cannot beat the market. They learn that they have not yet beaten it.

The lottery preference.

In the study’s sample, 93 per cent of traders were only options buyers. People overweight small probabilities, and a cheap option has the shape of a lottery ticket: a known small cost, an unknown vivid gain. Prospect theory says people will overpay for that shape, and they do. Options buyers had the highest incidence of loss, about 90 per cent. The sharpest number is their median return on capital employed, minus 114 per cent in FY26. Half of them lost more than the entire capital they had put to work.

Self-attribution.

No dataset observes this directly, but it holds the rest together. Gains are read as skill and losses as bad luck, and that asymmetry is what keeps overconfidence intact through a losing record.

The sunk cost fallacy, and the ego that feeds it.

Only 15.4 per cent of trader-quarters in the study were profitable. The median gain in a winning quarter was ₹4,366. The median loss in a losing quarter was ₹10,525, more than twice as large. Traders sat through losses far larger than the gains they banked, and at the level of the account that habit hardens into sunk cost. Traders with cumulative profits above ₹10 lakh during FY22 to FY24 continued trading at a rate of 88 per cent. Traders with cumulative losses above ₹10 lakh also continued at 88 per cent. Traders whose outcome, either way, was below ₹1 lakh continued at only 53 to 55 per cent. What predicts persistence is not whether you won. It is how much is at stake. Big winners stay because they believe they are good. Big losers stay because leaving now would make the loss permanent and admitted. They want to get back to even. Among the large past losers who continued, more than 95 per cent lost again.

What follows? Disclosure has done some work, but not enough, and the reason sits in the data. Every trader believes the aggregate describes someone else, so telling people that nine in ten lose money is a statistic about strangers. The design principle now should be to make each trader’s own record unavoidable, and to target named biases rather than risk in general.

Four measures are worth considering. Let the account’s own history be the credible witness: a personalised profit and loss statement at every login and each quarter end, showing the net outcome and all costs since account opening, in rupees and as a percentage of the trader’s own capital and portfolio. An appropriateness test at entry in place of a one-time consent screen, with graduated exposure limits for first-time traders. Self-set annual loss limits offered by every broker at onboarding, with a cooling-off period before a limit can be raised. And better framing at the order screen, with the premium shown as a share of capital at risk alongside the share of similar contracts that have expired worthless.

Mental accounting, used deliberately.

One more finding deserves to become the basis of investor education rather than another warning. Traders who lost more than ₹1 crore in derivatives held a median cash equity portfolio of about ₹138. For most of them the derivatives account was not a slice of a portfolio. It was the portfolio. Mental accounting, the habit of keeping money in separate mental jars, is usually filed as a bias. Made explicit, it is also the most workable remedy available. Individuals should be taught to allocate across three buckets: money that must stay safe, money that funds long-term goals through diversified market exposure, and a small aspirational bucket where the odds are poor and the loss is affordable. Futures and options belong in the third, sized in advance as a stated share of total wealth. That converts an open-ended activity into a budgeted one, and it gives a trader a number to check against. Brokers can carry this framing at onboarding, and investor education can make it the vocabulary: not do not trade, but decide first how much of your wealth this bucket is allowed to hold.

None of this should be mandated untested. SEBI now has the data and the broker relationships to run randomised trials of these nudges and see which change behaviour. Regulation has already done a great deal about the product, through expiry frequency, contract size and transaction costs. The frontier now is the account holder, and this study is the map.

Author – Rachana Baid, Dean – NISM

A Yen Rescue Dressed in Euros

A Yen Rescue Dressed in Euros

Washington’s intervention was ingenious in its plumbing and silent on the flows that matter most

On Friday, July 31, 2026, the United States stepped in to prop up the Japanese yen for the first time since 1998. The mechanics were stranger than the intervention itself: rather than selling dollars to buy yen — the textbook move — the Treasury sold euros to fund the purchase. That single choice turned a routine-sounding rescue into one of the year’s most debated maneuvers.

What happened

The yen had been in freefall, touching 160-plus to the dollar, its weakest since 1986, stoking importdriven inflation. Japan moved first and big, selling an estimated $53–59 billion of reserves to buy yen. Then the New York Fed, acting for the Treasury, sold euros for yen. The US contribution was never disclosed, though a photographed notepad in front of Treasury Secretary Scott Bessent read “Buy

Japanese Yen — $5–10 bil.” By the New York close the yen had firmed to around 157.40, and both governments confirmed the coordinated operation on the subsequent Monday.

The euro trick, and why the yen rose against the dollar

Here is the puzzle. When the US sold euros to buy yen, it never touched a single dollar — so why did the yen also strengthen against the dollar? Because the dollar, euro, and yen are mathematically tied together, so shifting one pair forces the others to realign. It unfolds in five stages.

  1. The starting balance. Normally the prices line up so no conversion route beats another. Using the July 31, 2026 rates — a dollar worth about 160 yen, a euro worth about 1.15 dollars — a euro was worth roughly 184 yen whether converted straight to yen or via dollars first.
  2. The targeted push. The US floods the market with euros to buy yen. This does two things at once: it makes the yen harder to get with euros, dragging the euro-yen rate down (say from 184 to 176), and it pushes the euro down against the dollar.
  3. The gap opens. Because the US never trades dollars, the dollar-yen rate stays put at 160 for the moment — creating a mismatch: it is now cheaper to get yen through euros than to buy them directly with dollars.
  4. Traders close the gap — and drag the dollar. Traders rush in to pocket that difference, taking the cheaper euro route in volume. Their buying pulls the dollar’s price down against the yen too, from 160 toward about 155. The dollar is dragged along by the other two.
  5. It all happens at once. In a live market these rates move together in the same instant, not one after another. The result: a stronger yen against the dollar, a slightly weaker dollar against the euro, and Washington’s dollar reserves left untouched. (This is just the US euro move; Japan was also selling dollars directly that day, so the real shift came from both.)

The starting rates above are the actual market rates on July 31, 2026; the post-intervention figures are illustrative, chosen to show the mechanism clearly.

Why bother? The Treasury-market motive

The reason has less to do with the yen than with the US bond market. Japan is the largest foreign holder of US Treasuries, and the fear was a doom loop: if Japan defended the yen alone by selling dollars, it might dump Treasurys to raise them, pushing US yields higher. Funding the operation with euros — and steering Japan toward the Fed’s FIMA (Foreign and International Monetary Authorities) repo facility, which lets foreign central banks borrow dollars against their Treasurys instead of selling them — let Washington lift the yen while shielding the Treasury market. Seen this way, it is genuinely clever: a currency operation reframed as a bond-market defense.

The blind spot: FIMA covers only the official channel

But the facility is open only to foreign central banks and official monetary authorities — and that is where the design springs a leak. It protects the Bank of Japan and the Ministry of Finance from dumping their own Treasurys, but does nothing for everyone else.

That “everyone else” is enormous. Japan’s $1.19 trillion in official Treasury holdings is only a slice of its foreign assets; Japan is the world’s largest net creditor, with net external assets near $3.7 trillion. On bonds alone, private Japanese institutions hold up to roughly $3 trillion in foreign bonds — dwarfing the official reserve stock FIMA protects by about three to one. Life insurers, banks, and pension funds piled in during years of near-zero yen yields; the Government Pension Investment Fund alone runs about $1.2 trillion. None of them qualify for FIMA. If they decide the yen has turned and repatriate — selling dollars and Treasurys to buy yen — they sell straight into the open market, exactly the pressure the facility was built to relieve for the BOJ(Bank of Japan). So the euro-and-repo architecture guards one channel of forced selling while leaving the far larger one wide open, and the Treasury-yield spike it was meant to prevent could arrive anyway.

The verdict

Both readings are partly true. As crisis management for the US bond market, the euro-funded maneuver is inventive and defensible. As a fix for the yen, it is almost certainly temporary and its safeguard only half-built: it left the fundamentals driving yen weakness intact and shielded only the official channel. Washington strengthened the right currency by selling the wrong one — and whether that reads as brilliance or improvisation depends on what the yen does next.

Disclaimer: 

  • Intervention figures are estimates; the US contribution was not officially disclosed.
  • Views are Personal.


Author – Kuldeep Thareja, DGM, NISM

The Closing Auction Needs Attendance, Not a Rethink

The Closing Auction Needs Attendance, Not a Rethink

A well-attended closing auction benefits investors by lowering trading costs, providing a closing price closer to fair value, and making capital raising cheaper for traded companies. India has recently established this mechanism. However, it now requires participants, and the industry best equipped to supply them is now attempting to understand it at present.

Since August 3, all Indian stocks with listed derivatives now close an auction from 3:20 to 3:30 pm, collecting orders with a random stop. During this period, orders are pooled, and the price that clears the highest volume is set as the close, replacing the previous volume-weighted average of the last half hour. Until recently, India was the only major market that closed based on an average rather than an auction.

The evidence behind that switch is worth stating plainly, because research of this kind rarely reaches the people who trade. In 2003, Pagano and Schwartz studied Euronext Paris after its introduction of a closing call in 1996 and 1998. They found that execution costs decreased and price discovery improved, primarily due to mechanical reasons. In continuous trading, large orders cross the spread and walk the book, incurring higher costs with each share. Conversely, during an auction, all orders clear at a single price. Similarly, Kandel, Rindi, and Bosetti in 2012 examined Borsa Italiana following its 2001 closing call, discovering increased efficiency because orders can be revised during auctions without execution, allowing participants to reveal true intentions rather than quoting defensively. Additionally, Butler, Grullon, and Weston in 2005 analysed 2,387 U.S. share sales from 1993 to 2000, finding that banks charged firms with more liquid stocks approximately 101 basis points less in fees—about one-fifth of the average—since the risk to underwriters decreases when the market is capable of absorbing the shares.

A study warns that we should pay close attention. Ellul, Shin, and Tonks (2005) analysed the London Stock Exchange following the introduction of a closing call to its SETS order book in May 2000. While the auction improved price discovery compared to the dealer system, it consistently struggled to clear smaller, less-liquid stocks. They attributed this to the externality of a thick market: an auction works only if participants expect others to be present. In thin markets, traders avoid participating, fearing a lack of counterparties, which confirms their fears. The fault isn’t in the design but in the lack of attendance.

India’s situation is revealing: data indicates that during MSCI rebalancing days, 73 to 83 percent of trading in impacted stocks takes place in the last half hour. Volatility during these times is two to over three times higher than the rest of the day, and the difference between the reference price and the close ranges from 61 to 404 basis points. Foreign portfolio investors account for 56 to 60 percent of the traded value, proprietary desks about 17 percent, retail roughly 11 percent, and domestic mutual funds only 8 to 9 percent. Meanwhile, the industry most dependent on an accurate closing value appears to be a bystander.

So, what specific actions can each type of fund perform within their current legal framework? Let’s begin with the hedged categories, which had approximately ₹11.4 lakh crore as of June 2026. An arbitrage fund is required to keep its equity exposure fully hedged—meaning it must be long the stock in cash and short the same stock in futures. This requirement enables it to sell into buy-heavy auctions: it owns the shares, and unwinding the hedge is its primary activity. This allows it to provide the sell side without actually shorting any stocks. Now that the derivative window extends to 3:40 pm and stock derivatives settle based on the auction price, both legs of the transaction settle at a single price. Equity savings funds carry the same hedged approach.

Balanced advantage funds can adjust their equity exposure within a broad range on any day. This flexibility allows them to respond to shortfalls in the auction by buying during sell-heavy close and selling during buy-heavy close, framing these actions as normal asset allocation rather than trading strategies. Active equity funds do not need additional approval for such moves. For example, a flexicap or multicap fund that plans to reduce a position can place that order at market close instead of gradually throughout the day, and a cash-holding fund can do the same. Value, contrarian, and dividend-yield funds have the clearest case for this approach, since buying what the index is selling aligns with their mandates.

The ceiling is equally real and serves as a regulatory limit. No fund engages in naked short selling, and during a cash auction, a fund can only sell what it can deliver, making capacity limited to its owned assets. Specialised Investment Funds, the only structure allowed to intentionally short, are capped at 25% of the portfolio and were valued at around ₹17,858 crore in mid-2026. Stock lending is limited, with only about 176 of the roughly 2,600 listed stocks eligible. Passive funds typically hold almost no cash to facilitate purchases, but SEBI has proposed allowing them to borrow overnight against auction positions.

There are substantial advantages for funds. They can execute large transactions at transparent prices with minimal market disruption, which is why regulators promote the auction as an alternative to the block-deal window. This leads to a higher net asset value each evening. Furthermore, as SEBI broadens the auction to include stocks beyond derivatives, funds that adapt quickly will gain access to a much larger pool of resources.

Aligning with global standards isn’t only about having a global closing mechanism but also about making it robust through active participation for mutual benefit. By mid-2025, foreign investors’ passive money amounted to around ₹20.5 lakh crore, representing nearly 29% of their Indian equity investments, while domestic passive funds held about ₹9.18 lakh crore. This money moves based on tracking error, which is determined at market close. A close that behaves like London’s allows global allocators to size India without factoring in discounts for execution risk. Ellul and his co-authors showed what happens when nobody turns up. The funds can make sure somebody does.

Authors: Rachana Baid (Dean, NISM), V Shunmugam (Partner, MCQube)


How “lifestyle creep” can derail your retirement plans

Most retirement plans do not fail because of one bad decision. They erode because of a hundred reasonable ones.

Lifestyle creep, the slow upward drift of spending as income rises, is rarely a story of extravagance. The people it affects most are usually doing everything right. They earn well, invest consistently, and meet their savings targets year after year. Nothing in their spending looks reckless, and nothing in their portfolio looks fragile. That is exactly what makes it hard to see.

When income is high, and savings goals are being met, an increase in spending rarely feels dangerous. In isolation, it isn’t. An annual holiday abroad. A larger home in a better location. A more expensive car. Each is a defensible decision made by a competent person with the money to make it.

The problem is that they are neither isolated nor temporary. They are small, permanent resets of what “normal” means. You do not experience them as expenditure. You experience them as your life. And once something has become your life, it stops being reviewed. Nobody sits down at the end of the year to ask whether the car you upgraded to was worth it. Slowly, your baseline spending ratchets upward while the mental model of your savings and investment stays where it was.

The biggest impact will be on your retirement income. A retirement corpus is anchored to the lifestyle you intend to continue, not the one you had when you drew up the plan. A permanent increase of, say, ₹1.5 lakh a month in living costs requires much more than ₹1.5 lakh in savings. Even assuming a conservative withdrawal rate, it requires several crores more in capital. When spending has crept up, a drawdown forces withdrawals from a shrunken portfolio at exactly the wrong moment, or a sharp cut in living standards at exactly the moment you have least appetite for one. Sequence-of-returns risk is not purely a market phenomenon; it is a function of how much you must pull out while prices are down.

Plan Your Retirement with Greater Financial Awareness

Understand how spending, saving and investing decisions can shape your financial future. Explore NISM’s investor education resources to build better financial awareness and make informed investment decisions


The reason why lifestyle creep goes unnoticed is that nothing feels out of control. The savings rate may still look respectable in absolute terms. The SIPs are running. The portfolio is growing. However, the ratio between what you spend and your investment corpus is never on your radar. By the time it surfaces, the changes are difficult to reverse because any downgrade in your lifestyle feels like failure. Much of it is structurally locked in – a larger home means higher maintenance charges and property tax. Choosing a prestigious school means a decade of commitment.

To ensure that lifestyle creep does not erode your retirement savings, three habits can help. First, track your savings rate, not your savings amount. A rising rupee figure can conceal a falling percentage. Second, price the lifestyle, not the purchase. Before a permanent upgrade, convert the monthly figure into the capital it implies. Third, pre-commit your salary raises. Decide what share will be invested and what share will go to upgrade your lifestyle.

The answer to lifestyle creep is not austerity. The answer is to act on it intelligently.

KOSPI Index: Korea’s Cascade, India’s Cushion

How The KOSPI Index Fell off a Cliff — and Why India’s Markets Didn’t Follow

Between mid-June and late July 2026 the South Korean benchmark (KOSPI) staged one of the most violent reversals in its history. After hitting an all-time high of roughly 9,386 on 19 June 2026, the index shed close to 27% in a matter of weeks, with repeated single-session crashes of 8–11% that tripped the Korea Exchange’s automated circuit breakers. By late July the exchange had logged around eight market-wide circuit breakers and nearly thirty sidecar halts in a single year (a sidecar is a milder, five-minute brake that suspends only automated program trading when index futures swing about 5%, whereas a circuit breaker halts the entire market) — surpassing the previous record set during the 2008 financial crisis. The slide was driven not by a single shock but by a combination of global macro pressures, sector-specific vulnerabilities, and deep structural weaknesses in Korea’s market. This piece examines those weaknesses, and contrasts them with the guardrails that have kept Indian markets comparatively orderly through the same global turbulence.

What Broke in South Korea

  • Extreme concentration in semiconductors. The KOSPI Index carries an unusually heavy structural tilt toward information technology and memory chips. Samsung Electronics and SK Hynix alone account for roughly 40–50% of the entire index. When global semiconductor sentiment cooled — amid missed earnings guidance from chipmakers and fears of AI-chip oversupply, sharpened by the rise of Chinese memory maker CXMT — these two stocks fell nearly 10–13% in single sessions and dragged the whole benchmark down with them. On the worst days, over 800 stocks declined against fewer than 50 that rose, showing how a two-stock problem became a whole-market problem.

  • Unwinding of leveraged AI positions. Through the AI rally, both retail and institutional investors amplified their bets on chip and tech names using single-stock ETFs and margin trading. As prices plummeted, forced liquidations and margin calls cascaded the downward spiral rather than cushioning it.

  • Global monetary policy and geopolitics. Stronger-than-expected U.S. data revived fears that the Federal Reserve would keep rates higher for longer. Combined with unexpected moves from the Bank of Korea and heightened friction in the Middle East, foreign capital exited Korean equities rapidly, adding currency pressure to the equity rout.

How India Absorbed the Same Shocks

The same global forces, the AI-chip wobble, persistent higher U.S. Fed rates, an oil-price scare, and a firm dollar struck Indian equities too. Yet the Nifty 50 Index and BSE Sensex moved close to flat, absorbing dips and recovering quickly, with no market-wide trading halts. Two structural features and a layered regulatory framework explain the difference.

  1. 1- Broad sectoral diversification

  2. Unlike Korea’s dependence on memory chips, India’s benchmarks are spread across roughly 13 sectors. Financial services is the single largest block at around 36%, followed by oil & gas (9.6%), Information Technology (8.37%), automobiles (7.13%), and consumer goods (5.7%), with no single stock dominating. Because the exposures are genuinely diversified, weakness in Indian IT was routinely offset by strength in banking, autos, or infrastructure, so no single theme could take the whole index down.

  3. 2- A domestic institutional backstop funded by SIPs

  4. India’s flow dynamics have shifted structurally. In the first half of the year Domestic Institutional Investors (DIIs) net-bought a record ₹4.3 lakh crore of Indian equities while Foreign Institutional Investors (FIIs) net-sold around ₹2.7 lakh crore. On individual panic days, DII buying repeatedly exceeded FII selling (for example, ₹9,283 crore of DII buying against ₹6,690 crore of FII selling over June 9–10, 2026). DII ownership has now structurally overtaken foreign ownership. As per NSE’s India Inc. Ownership Tracker data, DII ownership of NSE-listed companies surpassed their FPI counterparts. This reduces the “hot money” share of the market as SIP investors do not panic exit en masse.

Global market volatility creates both risks and opportunities.

Prepare yourself with the NISM Research Analyst Certification Examination to develop the knowledge required for equity research, market analysis, and informed investment recommendations.


The Indian Regulatory Guardrails

Beyond market structure, SEBI and the exchanges (NSE and BSE) have built multi-layered rules that actively limit concentration and speculative leverage before they can destabilise the market:

  • Index concentration norms. Since 2019, SEBI has required any index underlying an ETF or index fund to hold at least 10 stocks, cap any single stock at 25% (35% for sectoral/thematic indices), and limit the top three constituents to 65% combined. This directly forbids the kind of two-stock, 40–50% concentration that hollowed out the KOSPI Index.

  • Real-time margining. Brokers must collect upfront (peak) margins before execution, and positions are marked-to-market continuously. This prevents the build-up of unchecked leverage of the sort that triggered Korea’s cascade of margin-call liquidations.

  • Circuit breakers and price bands. Market-wide circuit breakers (at 10%, 15%, and 20% index moves) and scrip-level price bands halt runaway moves in an orderly way.

  • ASM and ESM surveillance. The Additional and Enhanced Surveillance Measures, introduced in 2018, let SEBI flag stocks showing unusual volatility, concentrated client trading, or suspicious price-volume patterns. Flagged stocks face 100% upfront margin and curbed intraday leverage — curbing speculative froth before it turns systemic.

 Takeaway

Korea’s fall was not simply bad luck; it was the predictable failure of a market concentrated in two stocks, one theme, and leveraged, foreign-heavy flows. India faced the same global shocks but was cushioned by genuine sectoral breadth, a deep and non-panicky domestic investor base built on SIPs, and a stack of SEBI rules that cap concentration and leverage by design.

Disclaimer: Views are personal.

Authors: Mitu Bhardwaj and Kuldeep Thareja DGMs, Centre for Content Creation, NISM

InvITs: an Avenue to Earn from Infrastructure Investments

Infrastructure Investment Trusts (INVITs): an Avenue to Earn from Infrastructure Investments

Infrastructure Investment Trusts (InvITs) sit in an interesting corner of the market: visible, listed, and yet not clearly understood. They are often pitched as “earn from toll roads” or “own power lines,” which is directionally correct but intellectually lazy. The reality is more nuanced, and more compelling if understood properly.

The Concept: what are you buying?

At their core, InvITs are trust structures that own and operate income-generating infrastructure assets – roads, transmission lines, gas pipelines, warehouses, telecom towers, etc. Securities and Exchange Board of India (SEBI) regulates them, and they are listed on stock exchanges, making them accessible like equities.

Think of them as the infrastructure equivalent of mutual funds. Instead of buying shares of companies, you are buying units of a vehicle that owns real assets i.e. differentiated from financial assets like stocks or bonds owned by mutual funds.

The structure is:

  • A sponsor (usually a developer like a power or road company) transfers assets into the trust;

  • An investment manager does financial management and capital structuring, declares distributions;

  • A project manager operates and optimizes these assets;

  • A trustee safeguards investor interest.

The key feature, and the real attraction, is distribution. InvITs are required to distribute at least 90 percent of their net distributable cash flows to unitholders. In simple terms: these are yield vehicles.

Investment Rationale

InvITs solve one basic portfolio problem: how to generate predictable cash flows without taking equity-like volatility.

There are four reasons why they deserve a serious look:

  1. 1. Predictable income (the core appeal)

  2. InvIT cash flows come from contracted or regulated assets – toll collections, transmission tariffs, or lease payments. These are not cyclical earnings in the traditional sense. This makes them closer to a high-yield bond than equity.

  3. 2. Inflation linkage

  4. Many infrastructure contracts have built-in escalation clauses (e.g. toll rates linked to inflation). This gives InvITs a rare characteristic: income that can keep pace with inflation, unlike fixed deposits.

  5. 3. Diversification benefit

  6. InvITs have low correlation with equities. They don’t move because of earnings upgrades or downgrades; they move based on interest rates, asset performance, and yield expectations.

  7. 4. Accessibility at small ticket size

For a small ticket size e.g. one unit in the secondary market / as per your corpus, you can access this asset class. Historically, infrastructure was a playground for sovereign funds and pension money. InvITs democratize access i.e. retail investors can now participate in these infrastructure assets.

The macro case for InvITs in India is:

  • India is entering an infrastructure buildout cycle;

  • Government programs like national monetization pipelines are feeding assets into InvIT structures;

  • The market itself is expected to grow significantly.

This creates a steady pipeline of new assets – roads, renewable energy, transmission networks, that can be monetized via InvITs. In essence, InvITs are becoming the financial bridge between public infrastructure needs and private capital.

How does the structure work?

At the core of every InvIT is Net Distributable Cash Flow (NDCF).

Cash flow waterfall illustration:

Step Component Typical Range (% of EBITDA)
1 EBITDA from assets 100%
2 Less: Interest cost (25–40%)
3 Less: Principal repayment (10–20%)
4 NDCF ~30–55%

Regulation requires ≥90% of NDCF to be distributed, which drives distribution yield mentioned earlier.

Implication:

  • Higher leverage → higher distributable yield

  • Stable assets → tighter yield band (8–10%)

  • Riskier assets → wider yield band (10–14%)

InvITs and expectations

Some of the InvITs in India are:

  • IndiaGrid Infra Trust (IndiGrid): Invests in power transmission, renewable energy and energy storage;

  • National Highways Infra Trust (NHAI InvIT): Backed by NHAI, focusing on road projects;

  • Vertis Infra Trust and Cube Highways Trust: Primarily holds road and highway assets;

  • Energy Infrastructure Trust: Involved in energy and gas pipeline projects;

  • Altius Telecom Infra Trust & NDR InvIT Trust engaged in telecom and warehousing sectors

Infrastructure Investment Trusts (InvITs) are often slotted into ‘alternatives’ for easy reference but they behave like listed yield instruments with embedded leverage. The leverage is, they avail of funding from banks or issuance of bonds, and deploy. The market narrative tends to oversimplify them as stable income products.

The distribution is largely a function of (a) distributable cash flow, (b) extent of leverage (funding availed) and (c) interest rate spreads i.e. difference between cost of funds and earnings from assets. As an example, if cost of funding is 8 percent and asset yield is 12 percent, interest spread is 4 percent. This spread drives equity yield and distribution growth potential.

Interested in exploring listed investment products like InvITs with greater confidence?

Build your market analysis skills through NISM’s Technical Analysis for Beginner eLearning Course and make more informed investment decisions.


Taxation

Nature of income Taxation for InvIT Taxation for unit-holders
Dividend Exempt Taxable or exempt, depending on SPV taxation regime. If the SPVs are operating under the old tax regime, it is exempt, otherwise taxable at marginal slab rate.
Interest Income Exempt Taxable at marginal slab rate
Capital Repayment Not an income,

hence not taxable

Non-taxable until the cumulative capital repayment exceeds the cost of acquisition, after which it is taxed at marginal slab rates.
Capital gain on sale of InvIT unit NA Same as equity / equity mutual funds, taxable at 12.5% after a holding period of 12 months, beyond Rs 1.25 lakh per financial year. Short term capital gains, for a holding period less 12 months, taxable at 20%.

The implication is, you need to track the breakup of distributions, not just total payouts. Not to worry, it is mentioned in the statement accompanying the distributions.

Where InvITs fit in a portfolio

For a perspective on how to look at InvITs, the broad guideline is:

  • A fixed-income alternative with relatively higher risk-return but, not an equity substitute;

  • A cash-flow generator, not a compounding machine like equity over a long period of time;

  • A portfolio diversifier, not a core growth allocation.

As an illustration, you may refer the following:

Asset Class Expected Return Volatility Correlation to Equity
Equity 12–15% High 1.0
Debt 6–8% Low ~0.2
InvITs 10–12% Medium ~0.4–0.6

Inference:

  • Higher return than debt

  • Lower volatility than equity

  • Moderate diversification benefit

InvITs won’t outperform equities in a bull market. These won’t protect fully in a rate shock. But in a portfolio context, they offer something rare: visible cash flows with moderate return certainty. And in markets where most returns are narrative-driven, that kind of predictability is a feature, not a limitation.

Author : Joydeep Sen is a corporate trainer (financial markets) and author

© 2026 National Institute of Securities Markets (NISM). All rights reserved.