Notifications 15
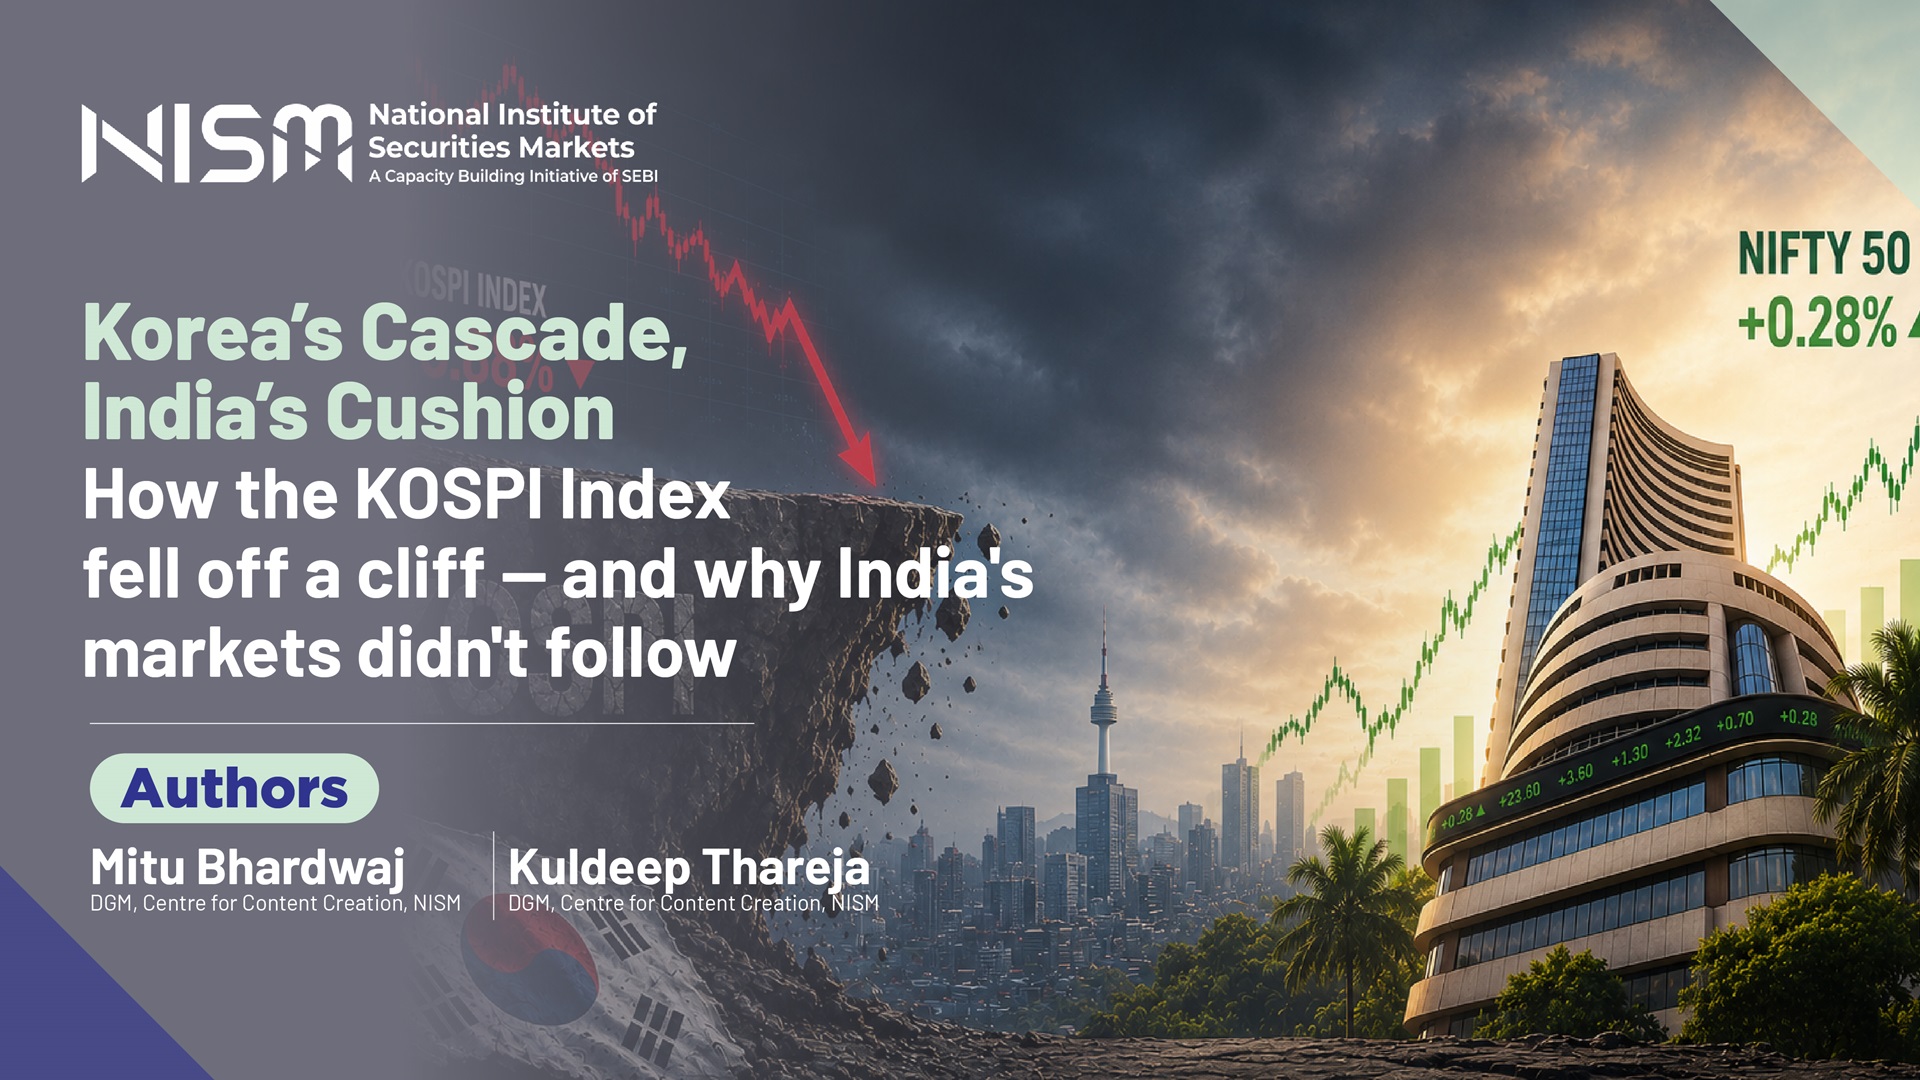
Between mid-June and late July 2026 the South Korean benchmark (KOSPI) staged one of the most violent reversals in its history. After hitting an all-time high of roughly 9,386 on 19 June 2026, the index shed close to 27% in a matter of weeks, with repeated single-session crashes of 8–11% that tripped the Korea Exchange’s automated circuit breakers. By late July the exchange had logged around eight market-wide circuit breakers and nearly thirty sidecar halts in a single year (a sidecar is a milder, five-minute brake that suspends only automated program trading when index futures swing about 5%, whereas a circuit breaker halts the entire market) — surpassing the previous record set during the 2008 financial crisis. The slide was driven not by a single shock but by a combination of global macro pressures, sector-specific vulnerabilities, and deep structural weaknesses in Korea’s market. This piece examines those weaknesses, and contrasts them with the guardrails that have kept Indian markets comparatively orderly through the same global turbulence.
The same global forces, the AI-chip wobble, persistent higher U.S. Fed rates, an oil-price scare, and a firm dollar struck Indian equities too. Yet the Nifty 50 Index and BSE Sensex moved close to flat, absorbing dips and recovering quickly, with no market-wide trading halts. Two structural features and a layered regulatory framework explain the difference.
Unlike Korea’s dependence on memory chips, India’s benchmarks are spread across roughly 13 sectors. Financial services is the single largest block at around 36%, followed by oil & gas (9.6%), Information Technology (8.37%), automobiles (7.13%), and consumer goods (5.7%), with no single stock dominating. Because the exposures are genuinely diversified, weakness in Indian IT was routinely offset by strength in banking, autos, or infrastructure, so no single theme could take the whole index down.
India’s flow dynamics have shifted structurally. In the first half of the year Domestic Institutional Investors (DIIs) net-bought a record ₹4.3 lakh crore of Indian equities while Foreign Institutional Investors (FIIs) net-sold around ₹2.7 lakh crore. On individual panic days, DII buying repeatedly exceeded FII selling (for example, ₹9,283 crore of DII buying against ₹6,690 crore of FII selling over June 9–10, 2026). DII ownership has now structurally overtaken foreign ownership. As per NSE’s India Inc. Ownership Tracker data, DII ownership of NSE-listed companies surpassed their FPI counterparts. This reduces the “hot money” share of the market as SIP investors do not panic exit en masse.
Beyond market structure, SEBI and the exchanges (NSE and BSE) have built multi-layered rules that actively limit concentration and speculative leverage before they can destabilise the market:
Korea’s fall was not simply bad luck; it was the predictable failure of a market concentrated in two stocks, one theme, and leveraged, foreign-heavy flows. India faced the same global shocks but was cushioned by genuine sectoral breadth, a deep and non-panicky domestic investor base built on SIPs, and a stack of SEBI rules that cap concentration and leverage by design.
Disclaimer: Views are personal.
Authors: Mitu Bhardwaj and Kuldeep Thareja DGMs, Centre for Content Creation, NISM
Last Updated on: October 29, 2026 If you’re confused about capital gains tax on your investments in listed shares, mutual…
Trusting AI with your money is subject to market risks If you have asked ChatGPT, Gemini or Claude any money…
Why are retail investors voting with their wallets for passive products? The Assets under Management (AuM) of passive equity funds,…
© 2026 National Institute of Securities Markets (NISM). All rights reserved.
